Showing posts with label Global Housing Watch. Show all posts
Thursday, March 24, 2016
Breaking the Link between Housing Cycles, Banking Crises, and Recession
“By not reflecting liquidity risks in capital requirements, banking and insurance regulators have conjured up a dangerous system in which financial firms without liquidity take liquidity risks and financial firms with liquidity fail to do so. Two simple regulatory steps could change this system. Financial firms need to maintain a long-term stable funding ratio, and the regulatory risk weightings of assets should take into account the maturity of liabilities. These changes would encourage institutions with liquidity (life insurers, pension funds, and others with long-term liabilities) to provide it through instruments such as the self-rescheduling mortgage. They would also encourage banks to sell their illiquid assets to institutions with liquidity or lighten their dependency on short-term funding. Read the full article…
Posted by at 9:00 AM
Labels: Global Housing Watch
Wednesday, March 23, 2016
Monetary Policy and Financial Stability: Canada’s House-Price Dilemma
Canada’s housing market is sizzling hot and the Bank of Canada has a monetary policy dilemma: increase interest rates to cool the housing market would hurt borrowers and the economy; keep interest rates low adds fuel to the borrowing that led to the rise in housing prices and in household debt. What to do?
Housing headache
The latest national data on house prices in February suggest a year-on-year increase of 9 percent. House prices in Vancouver and Toronto—that contribute about a third of Canada’s GDP—have led the increase.
Canada’s housing boom has been accompanied by a steady rise in the nation’s household debt to 165 percent of disposable income by the end of 2015 (see chart). One way to cool the housing sector is to increase interest rates, but that would hurt the slowing economy, which has been hit hard by the decline in oil prices. Hence, the dilemma.

Low mortgage rates are an important factor feeding the housing market boom. This has helped keep interest payments low even as the size of the average mortgage has risen. As the figure shows, the share of interest payments in households’ disposable income has declined from 9 percent in 2008 to 6 percent in 2015, while the average size of mortgages has increased by some 40 percent over the same period. This means more households are able to afford more expensive homes, which, in turn, prompts households to borrow more money and get further into debt, while house prices continue to be pushed upward. This process should continue as long as employment is robust and interest rates remain low.
The Bank of Canada is rightly concerned about the rise in household debt, which makes the economy more vulnerable to unanticipated shocks and financial strains more probable. A mini version of this is playing out in Alberta, which has the third highest level of household debt among the provinces—after British Colombia and Ontario—and was hit by a large terms of trade shock from the oil price decline. The Alberta economy is expected to have contracted by almost 2 percent last year amid massive layoffs by the oil industry and house prices fell by 4 percent since their peak in late 2014.
Continue reading here.
Via iMFdirect:
Canada’s housing market is sizzling hot and the Bank of Canada has a monetary policy dilemma: increase interest rates to cool the housing market would hurt borrowers and the economy; keep interest rates low adds fuel to the borrowing that led to the rise in housing prices and in household debt. What to do?
Housing headache
The latest national data on house prices in February suggest a year-on-year increase of 9 percent.
Posted by at 9:00 AM
Labels: Global Housing Watch
Monday, March 21, 2016
Financial Stability and Interest-Rate Policy
The paper notes that “At the current conjuncture Canada represents an interesting case: Monetary policy faces the dilemma of supporting a struggling economy by cutting interest rates and maintaining financial stability in a context of high household debt and ever growing housing prices.”
The paper’s “findings show that it is very unlikely that the benefits of having a meaningfully tighter policy (i.e., at least 25 basis points higher than otherwise) would outweigh its costs, in the current Canadian context. In fact, even though the interest rate increase reduces the growth of real household credit and house prices and the ratio of household debt to GDP, the reduction in the crisis probability is minor and peaks only after about 8 years. At the same time, costs are front loaded and magnified by the tighter economic conditions. The policy rate path which takes into account financial stability risks is, thus, only 6 basis points higher than otherwise (for 8 quarters)—which, quantitatively, is not a meaningful policy alternative. A policy rate that is 25 basis points higher than otherwise (for 8 quarters) is expected to be welfare improving only under a scenario where a crisis would impose severe costs on the economy and real credit is expected to grow (in absence of policy intervention) at or above 9 percent a year for the next 3 consecutive years.”
“Should monetary policy use its short-term policy rate to stabilize the growth in household credit and housing prices with the aim of promoting financial stability? (…) the answer is no— especially when the economy is slowing down”, according to a new IMF working paper by Andrea Pescatori and Stefan Laseen–Financial Stability and Interest-Rate Policy: A Quantitative Assessment of Costs and Benefits.
The paper notes that “At the current conjuncture Canada represents an interesting case: Monetary policy faces the dilemma of supporting a struggling economy by cutting interest rates and maintaining financial stability in a context of high household debt and ever growing housing prices.”
Posted by at 7:50 PM
Labels: Global Housing Watch
Wednesday, March 16, 2016
House Prices in Indonesia

“Property prices have been subdued, in tandem with slowing economic growth and weak business sentiment”, notes IMF’s report on Indonesia.
Posted by at 9:00 AM
Labels: Global Housing Watch
Friday, March 11, 2016
House Prices in Montenegro
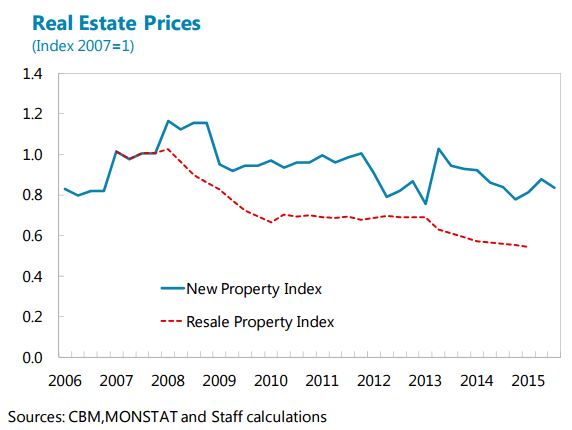
“Property prices have continued to fall from their crisis peaks, in part because Russian buying has fallen”, notes the IMF’s report on Montenegro.
Posted by at 10:00 AM
Labels: Global Housing Watch
Subscribe to: Posts